Manufacturing is entering a new investment cycle as technology begins to reshape not only how products are made, but how industrial businesses are built. Historically, the sector favored scale, specialized assets and long operating histories. Today, a growing number of companies are entering the market through narrower, technology-enabled points of advantage: automating a specific process, improving equipment productivity, reducing material intensity, shortening production time or introducing a more flexible manufacturing method. This is lowering the threshold for innovation and creating new business models across the industrial value chain.
The shift is being supported by a combination of structural pressures and improving technology economics. Manufacturers continue to face skilled-labor shortages, constrained capacity, rising operating costs and pressure to strengthen supply chains. At the same time, sensing, machine vision, computing, robotics and industrial software have become more capable and more affordable. The result is a stronger economic case for technologies that can improve throughput, reduce downtime, raise quality or make existing assets more productive.
This is changing where new companies are being built. Rather than competing only as traditional equipment manufacturers, businesses are increasingly combining hardware, software and domain expertise. Some are building intelligent machinery around specific industrial workflows. Others are adding digital layers to existing equipment, allowing operators to monitor performance, predict failures or automate decisions. A third group is developing new production methods that reduce tooling requirements, improve material efficiency or enable products that would be difficult to manufacture conventionally.
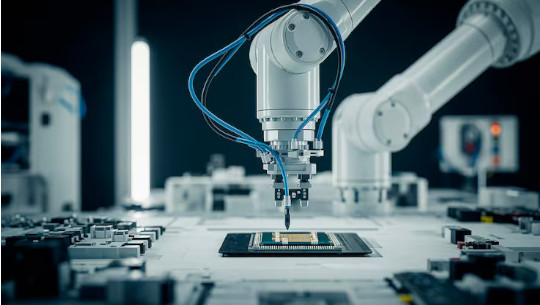
Automation remains a major part of this transition, but the opportunity is broader than robotics alone. The important development is the move from fixed automation toward more flexible systems. Machine vision, autonomous equipment, advanced controls and AI-enabled software are making it possible to automate processes that historically involved too much variation for conventional systems. This expands the addressable market from highly repetitive manufacturing into a wider range of industrial applications.
Artificial intelligence strengthens that shift by making industrial systems more responsive. Its most relevant applications are tied directly to production economics: identifying quality issues earlier, predicting equipment failures, optimizing scheduling, improving process control and supporting engineering decisions. Physical AI extends this further by connecting intelligence with machinery, enabling equipment to perceive its environment and operate with greater autonomy. The significance is not the technology itself, but the possibility of reducing the amount of manual intervention required across complex industrial workflows.
At the same time, advanced manufacturing is expanding beyond automation. Additive processes, precision manufacturing, advanced materials and new forms of industrial engineering are changing the cost and design constraints of physical production. These technologies can reduce component complexity, shorten development cycles, lower material waste or enable higher-performance products. In many cases, this creates value on both sides of the equation: better production economics and a differentiated end product.
The sector is also becoming more attractive because many technologies can be introduced incrementally. A company does not need to replace an entire production system to create value. It can solve one expensive problem—inspection, machining, maintenance, material handling, energy use or process control—and build from that initial point of adoption. If the product demonstrates a clear return, expansion can follow across additional workflows, sites or end markets. This gives new companies a more practical path into industries that were historically difficult to penetrate.
That expansion model can also create favorable economics. Industrial customers are generally slower to adopt new technologies, but once a product becomes integrated into a critical process, replacement can be disruptive and costly. This can create long customer relationships, embedded workflows and meaningful switching friction. Businesses that combine strong technical differentiation with recurring service, software or aftermarket revenue may therefore achieve a more attractive economic profile than traditional industrial companies.
The broader opportunity is increasingly visible across areas such as intelligent equipment, automation, industrial software, advanced production systems, sensing, machine vision and resource efficiency. What links these categories is not a common technology, but a common economic objective: improving the productivity of physical assets and industrial processes. That gives the sector a clearer investment framework than simply categorizing companies as robotics, AI or advanced manufacturing.
For investors, manufacturing is increasingly presenting opportunities across automation, intelligent equipment, industrial software, advanced production systems, machine vision and resource efficiency. The strongest businesses are likely to combine measurable customer ROI with reliable deployment, deep integration into industrial workflows and room to expand across applications or end markets. As technology becomes more embedded in production, these characteristics can support durable growth, defensibility and long-term value creation.
Aceana Group, Insights